When is South Africa's next repo rate decision?
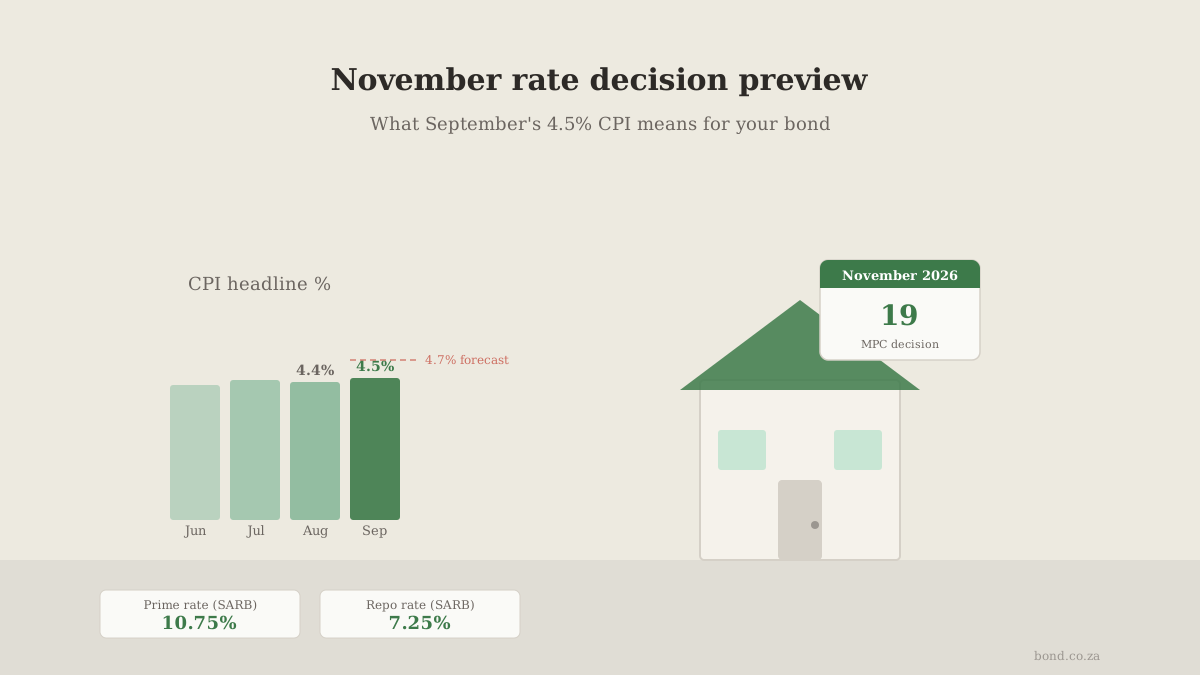
The next repo rate decision in South Africa falls on 19 November 2026, when the Monetary Policy Committee concludes its final meeting of 2026. The statement is released at approximately 15:00 SAST, per the SARB's official MPC calendar. Rates in force today: repo 7.25% and prime 10.75%, effective 25 September 2026, after the committee's unanimous 25 basis point hike — the second of 2026, following May's move.
What did September's CPI print show?
September 2026 headline CPI came in at 4.5%, published by Stats SA on 21 October in its P0141 release. The print rose from 4.4% in August but landed below the 4.7% median forecast of 17 economists surveyed by Bloomberg. A below-forecast print eases some of the pressure on the committee — although inflation remains well above the 3% goal the SARB has now adopted, and the September MPC statement flagged fuel and services inflation pressure when it hiked.
It is also the last reading the committee can act on: October 2026 CPI only publishes in late November, after the decision. Whatever the MPC says on the 19th will rest on data through September — plus the SARB's own inflation forecast, fuel prices, the exchange rate and global conditions.
Will the SARB hold or hike in November?
Market consensus, as reported by Trading Economics ahead of the meeting, points to a hold at 7.25% — and the Governor's own public comments point the same way. Kganyago said in early November that prevailing rates are high enough to return inflation to target, while forward-rate agreements tracked in the Moneyweb/Bloomberg report still price further hikes over the next year — which argues against loosening. After two hikes and a unanimous September vote, the path of least resistance is a pause.
This is not a forecast. The MPC decides on the day and a surprise in either direction remains possible: the below-forecast CPI supports patience, but the committee's stated concern about second-round price effects and the 2026 hiking record show it is willing to move. bond.co.za's previews of whether the repo rate goes up or down in November cover both cases in detail.
What would a 25bp hike on 19 November cost on your bond?
If the committee raises by another 25 basis points, prime would move from 10.75% to about 11.00%. If it holds, repayments stay exactly where they are. bond.co.za's calculation, at prime with no margin over 20 years:
| Bond size | Hold at 10.75% | Hike to 11.00% | Extra / month |
|---|---|---|---|
| R 1 000 000 | R 10 152 | R 10 322 | +R 170 |
| R 1 500 000 | R 15 228 | R 15 483 | +R 254 |
| R 2 000 000 | R 20 305 | R 20 644 | +R 339 |
| R 2 500 000 | R 25 381 | R 25 805 | +R 424 |
These figures are estimates assuming prime with no margin and a 20-year term. Your actual rate may be prime plus or minus a margin, set by the bank based on your credit profile, deposit size and loan-to-value. Use the bond repayment calculator to run both scenarios at your own rate.
What should home buyers do before the 19 November decision?
If you are buying in the next one to three months, getting pre-approved now locks in what you qualify for at 10.75% prime. Pre-approval certificates are typically valid for 90 days — long enough to cover the decision and its aftermath. Under the National Credit Act, banks assess affordability against gross monthly income, with the standard rule of thumb that the repayment should not exceed about 30% of it; a hold keeps that ceiling where it is, while a hike compresses it further. Check your qualifying amount with the home loan affordability calculator.
A bond originator submits your application to multiple banks simultaneously, which typically produces a better rate than a single-bank application — the industry average rate concession across originator-submitted applications was 0.67 percentage points below prime, per ooba Home Loans data (as at 3 October 2026). To apply for pre-approval or compare what bond.co.za can offer, the process takes about 10 minutes online. If you are weighing a fixed rate against staying variable before the decision, read our fixed vs variable comparison first.
(Published 8 November 2026. Rate figures verified against the SARB September 2026 MPC statement. September 2026 CPI per Stats SA P0141 via Moneyweb/Bloomberg, 21 October 2026. Market-consensus framing per Trading Economics. Repayment examples: 20-year term at prime, no margin — your actual rate may differ.)