What is the current inflation rate in South Africa today?
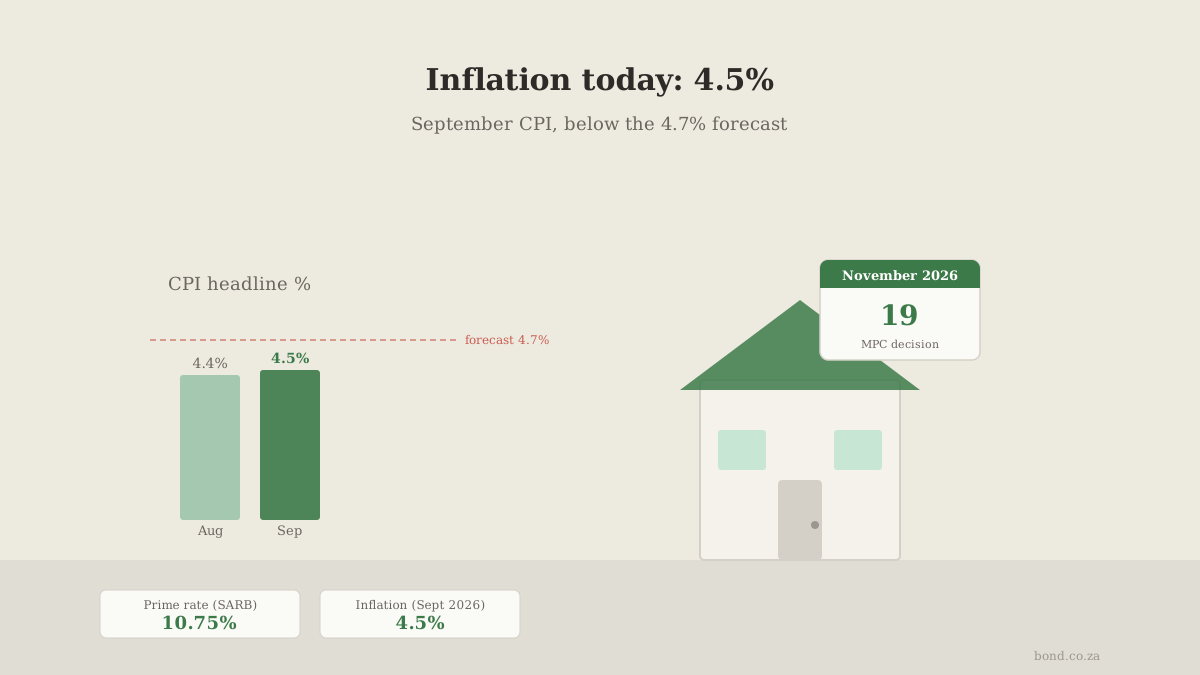
The current inflation rate in South Africa is 4.5%, as at 21 October 2026, per Stats SA's Consumer Price Index P0141 release. That is the annual increase for September 2026: the same basket of consumer goods and services cost 4.5% more than in September 2025. The previous reading, for August 2026, was 4.4%. The figure matters for home owners because the South African Reserve Bank sets the repo rate — currently 7.25%, effective 25 September 2026 — to steer inflation, and prime, now 10.75%, is the benchmark variable-rate home loans are priced against.
Why did September inflation come in below the forecast?
Most economists expected a bigger rise. The median estimate of 17 economists in a Bloomberg survey was 4.7%, per Moneyweb's report of 21 October 2026 — yet the actual print was 4.5%. The report noted the increase came even after energy prices soared on supply constraints linked to the conflicts in Ukraine and the Middle East. Fuel prices hit a record in October 2026 and are set to rise again in November, so the report expects inflation to keep accelerating — September's below-forecast reading is a data point, not a reversal of that trend.
What does 4.5% inflation mean for the November rate decision?
The MPC next decides on 19 November 2026, and the September print is the last major inflation reading it will see. A 4.5% print sits exactly at the midpoint of the SARB's 3–6% inflation band, and Governor Lesetja Kganyago has repeatedly said policymakers remain committed to getting inflation back to their 3% goal (per the Bloomberg report of 21 October 2026). The committee raised the repo rate by 25 basis points to 7.25% on 25 September 2026 — a unanimous vote. Below-forecast inflation does not guarantee a hold in November: the MPC is forward-looking, and with fuel set to rise again, the decision remains open.
What are markets pricing for South African interest rates next?
Forward-rate agreements — the instruments traders use to speculate on borrowing costs — are pricing in two more rate hikes over the next year, per the Moneyweb/Bloomberg report of 21 October 2026. Each hike is 25 basis points. If both landed, prime would move from 10.75% to about 11.25%. bond.co.za's calculation, at 20 years and prime with no margin:
| Bond size | Today at 10.75% | One hike (11.00%) | Two hikes (11.25%) | Extra / month |
|---|---|---|---|---|
| R 1 000 000 | R 10 152 | R 10 322 | R 10 493 | +R 340 |
| R 1 500 000 | R 15 228 | R 15 483 | R 15 739 | +R 510 |
| R 2 000 000 | R 20 305 | R 20 644 | R 20 985 | +R 681 |
| R 2 500 000 | R 25 381 | R 25 805 | R 26 231 | +R 851 |
These figures are estimates assuming prime with no margin and a 20-year term. Your actual rate may be prime plus or minus a margin, set by the bank based on your credit profile, deposit size and loan-to-value. Market pricing can change before the next decision. Run your own numbers with the bond repayment calculator or check what you qualify for today with the home loan affordability calculator.
What should home buyers do before the next MPC decision?
If you are buying in the next one to three months, getting pre-approved now locks in what you qualify for at 10.75% prime. Pre-approval certificates are typically valid for 90 days — covering the 19 November 2026 decision and its aftermath. A bond originator submits your application to multiple banks simultaneously, which typically produces a better rate than a single-bank application — the industry average rate concession across originator-submitted applications was 0.67 percentage points below prime, per ooba Home Loans data (as at 3 October 2026). To apply for pre-approval or compare what bond.co.za can offer, the process takes about 10 minutes online.
(Published 25 October 2026. Rate figures verified against the SARB September 2026 MPC statement. Inflation figures 4.5% (September 2026) and 4.4% (August 2026) per Stats SA P0141, published 21 October 2026; forecast and market-pricing context per Moneyweb/Bloomberg, 21 October 2026. Repayment examples: 20-year term at prime, no margin — your actual rate may differ.)