What is Stats SA publishing today, and why does it matter for home loans?
Stats SA releases Consumer Price Index data under its P0141 statistical release each month. The September 2026 edition publishes today, 21 October 2026. It measures price changes across food, fuel, housing, transport and services — and it is the final major inflation print the Monetary Policy Committee can see before it meets on 19 November 2026.
The SARB sets the repo rate — currently 7.25%, effective 25 September 2026 — to keep inflation within the 3–6% band. When CPI rises toward or above the 4.5% midpoint, the committee faces pressure to tighten. Prime follows repo at repo plus 3.5 percentage points, and prime is the benchmark every variable-rate home loan in South Africa is priced against. A CPI reading that influences the November decision will flow directly into what you pay on your bond.
What was South Africa's headline inflation before today?
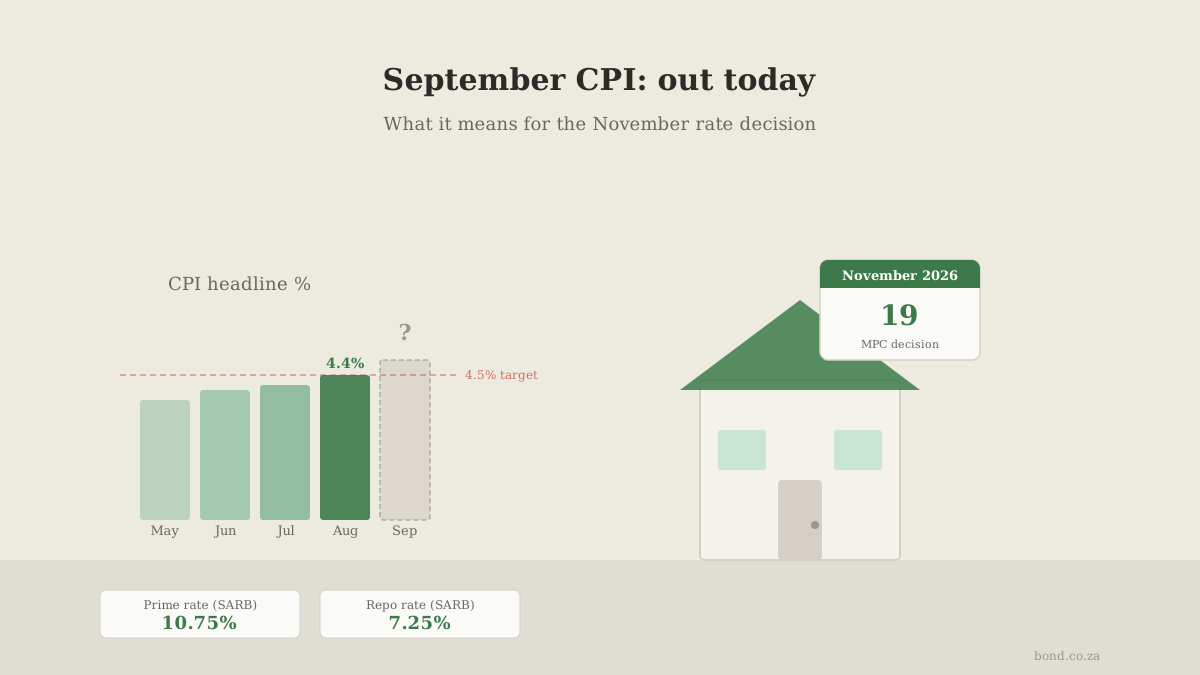
The SARB September 2026 MPC statement (23 September) cited headline inflation of 4.4% in its deliberations — the most recently confirmed figure as at that meeting. The committee described fuel prices as rising again after moderating between June and August, and services inflation as elevated. On those conditions, the committee raised the repo rate unanimously by 25 basis points — a second hike in 2026, following May's move.
The SARB's preferred inflation midpoint is 4.5%. A September reading below 4.4% would show the trend moderating toward target; a reading above 4.4% would reinforce the committee's concern about second-round price effects. Neither direction guarantees a particular November outcome — the MPC considers exchange rate movements, oil prices, global growth and domestic demand alongside CPI.
The confirmed September 2026 CPI figure was not yet available for this article at publication time. Verify the number directly at statssa.gov.za — P0141. bond.co.za will update this article when the figure is confirmed.
What would a November rate hike cost on your bond?
If September CPI prints above the SARB's comfort zone and the committee raises by another 25 basis points on 19 November 2026, prime would move from 10.75% to about 11.00%. bond.co.za's calculation, at 20 years and prime with no margin:
| Bond size | Hold at 10.75% | Hike to 11.00% | Extra / month |
|---|---|---|---|
| R 1 000 000 | R 10 152 | R 10 322 | +R 170 |
| R 1 500 000 | R 15 228 | R 15 483 | +R 254 |
| R 2 000 000 | R 20 305 | R 20 644 | +R 339 |
| R 2 500 000 | R 25 381 | R 25 805 | +R 424 |
These figures are estimates assuming prime with no margin and a 20-year term. Your actual rate may be prime plus or minus a margin, set by the bank based on your credit profile, deposit size and loan-to-value. Use the bond repayment calculator to run both scenarios at your own rate.
What would a November hold mean for bond affordability?
If the MPC holds at the November meeting, prime stays at 10.75% — the rate that took effect on 25 September 2026 after September's unanimous decision. The 2026 rate cycle has already added 50 basis points to prime since May (10.25% → 10.75%). A hold on 19 November would give the rate cycle a pause, leaving monthly repayments stable at current levels and giving buyers who pre-approved at 10.75% a window before any further change.
Under the National Credit Act, banks assess home-loan affordability against gross monthly income — the standard industry rule of thumb is that the monthly repayment should not exceed about 30% of gross income. A hold keeps that ceiling where it is; a hike compresses it further. Buyers active now can check their qualifying amount against current rates using the home loan affordability calculator.
How does the SARB use CPI data in its rate decisions?
The Monetary Policy Committee does not mechanically move the repo rate every time CPI changes. It builds a forward-looking inflation forecast using CPI data, import prices, fuel prices, services costs, exchange-rate pass-through and global economic conditions. It then decides whether the current policy rate is consistent with returning inflation to the 3–6% band in its projection window.
One CPI print rarely determines a decision alone. September 2026 CPI matters because it is the last available inflation reading before the November meeting — the committee cannot see October CPI before it decides. A surprise in either direction from 4.4% would update the committee's inflation trajectory, but a single data point does not override the accumulated 2026 record: two hikes, a unanimous September vote, and stated concern about second-round effects.
What should SA home buyers do before the 19 November decision?
If you are buying in the next one to three months, getting pre-approved now locks in what you qualify for at 10.75% prime. Pre-approval certificates are typically valid for 90 days — long enough to cover a November decision and its aftermath. If the committee holds, your pre-approved amount remains valid; if it hikes, banks will reassess new applications at the higher rate.
A bond originator submits your application to multiple banks simultaneously, which typically produces a better rate than a single-bank application — the industry average rate concession across originator-submitted applications was 0.67 percentage points below prime, per ooba Home Loans data (as at 3 October 2026). To apply for pre-approval or compare what bond.co.za can offer, the process takes about 10 minutes online.
(Published 21 October 2026. Rate figures verified against the SARB September 2026 MPC statement. September 2026 CPI figure pending Stats SA P0141 release today. CPI reference of 4.4% sourced from: September 2026 MPC statement, 23 September 2026. Repayment examples: 20-year term at prime, no margin — your actual rate may differ.)